
Housing Market Today: Best Home Prices & Mortgage Rates Guide
The Housing Market Today is changing as buyers, sellers, and investors respond to shifting mortgage rates, home prices, and housing inventory. Whether you are purchasing your first home, planning to sell, or looking for investment opportunities, understanding the latest real estate trends can help you make informed decisions.
In recent months, affordability has remained one of the biggest concerns. Mortgage rates continue to influence buyer demand, while limited housing inventory has kept prices elevated in many regions. At the same time, economists are closely watching inflation, employment, and central bank policies for clues about where the housing market could head next.
This guide explains what’s happening in today’s housing market, why mortgage rates matter, how home prices are changing, and what experts expect in the coming months.
🔄 Editor’s Update (August 2026)
Update: Search interest in the Housing Market Today continues to grow as homebuyers and homeowners look for the latest mortgage rates, housing affordability trends, and home price forecasts.
Recent market data shows that mortgage rates remain one of the biggest factors affecting affordability, while housing inventory continues to vary by region. This guide has been updated with the latest housing market insights, mortgage rate trends, affordability analysis, and expert guidance to help readers better understand today’s real estate market.
💡 EEZYPOST Insight
Many buyers focus only on mortgage interest rates, but true housing affordability depends on several factors working together. Home prices, property taxes, homeowners insurance, monthly income, down payment size, and local inventory all affect whether a home fits your budget. Even if mortgage rates decline, affordability may remain challenging if home prices continue rising.
Why Housing Affordability Still Matters
Housing affordability depends on more than the price of a home. Mortgage rates, monthly housing payments, household income, property taxes, homeowners insurance, and available inventory all influence whether buyers can realistically afford a property. When mortgage rates remain elevated, even a modestly priced home can carry a much higher monthly payment.
That is why the housing market today can look different from one region to another. Buyers in markets with lower home prices, stronger incomes, or more available inventory may have better options, while buyers in expensive markets can still face significant affordability pressure even when home-price growth slows.
⚡ Quick Answer
The Housing Market Today remains challenging due to elevated mortgage rates, limited housing inventory, and affordability concerns. While home prices have stabilized in some areas, local market conditions vary. Buyers should compare mortgage rates, monitor inventory, and evaluate affordability before making a purchase or investment decision. Housing market affordability depends largely on current mortgage rates, home prices, local inventory, and household income, making it essential for buyers to evaluate all costs before purchasing a home.
What Is Happening in the Housing Market Today?
The Housing Market Today is shaped by several key factors, including mortgage rates, housing inventory, home prices, inflation, and overall economic conditions. While demand for homes remains steady in many areas, affordability challenges continue to influence buyer behavior.
According to the National Association of Realtors (NAR), housing inventory and buyer activity continue to play a major role in shaping real estate market conditions across the United States.
One of the biggest changes has been the limited supply of available homes. Many homeowners are choosing to keep their existing low-interest mortgages instead of selling, which has reduced inventory in several markets. As a result, buyers often face increased competition for well-priced properties.
Despite higher borrowing costs, demand has not disappeared. First-time home buyers, growing families, and real estate investors continue to enter the market, although many are taking longer to make purchasing decisions. Local conditions vary significantly, making it essential to research regional market trends before buying or selling a property.
Why Mortgage Rates Matter
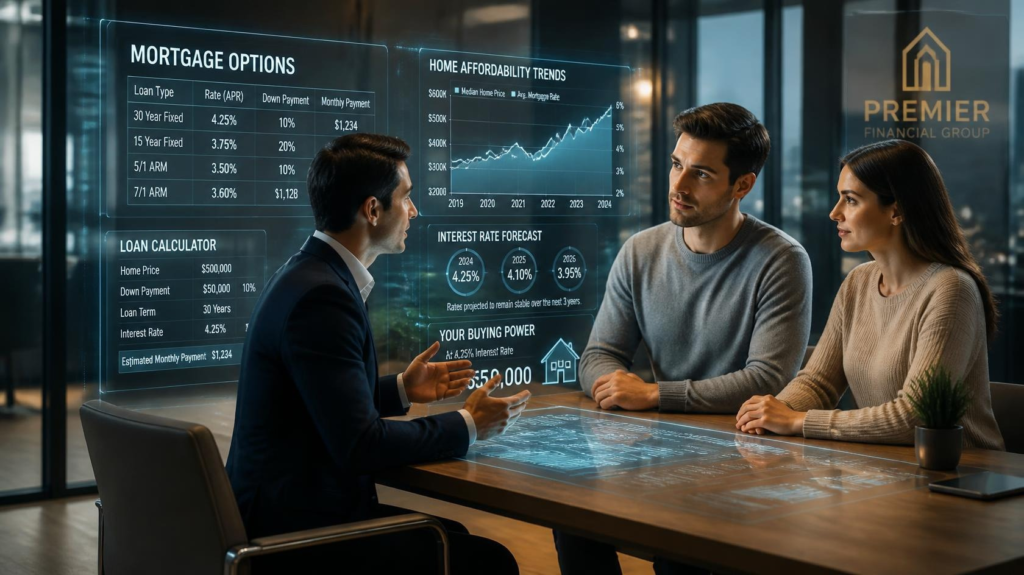
Mortgage rates play a major role in determining how affordable a home purchase will be. Even a small increase in interest rates can significantly raise monthly mortgage payments, reducing the amount buyers can comfortably afford.
Weekly mortgage rate data published by Freddie Mac’s Primary Mortgage Market Survey provides valuable insights into borrowing costs
When mortgage rates increase:
- Monthly mortgage payments become more expensive.
- Some buyers postpone purchasing a home.
- Demand may slow in certain markets.
- Sellers may need to adjust pricing expectations.
On the other hand, lower mortgage rates generally encourage more buyers to enter the market, increasing competition and supporting home values.
Financial experts closely monitor inflation and decisions by central banks because these factors often influence future borrowing costs. Anyone planning to buy a home should compare lenders, understand loan options, and calculate the total cost of ownership rather than focusing only on the purchase price.
Are Home Prices Rising or Falling?
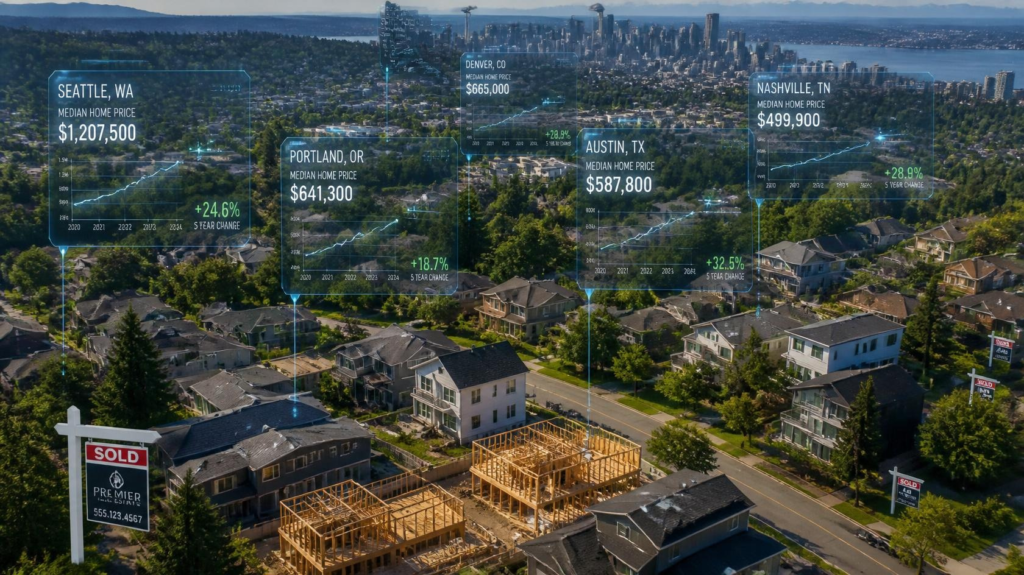
Home prices continue to vary depending on location, housing supply, local demand, and economic conditions. In many metropolitan areas, limited inventory has helped support property values, while some regions have experienced slower price growth as buyers become more cautious.
Instead of a nationwide decline, many experts expect the market to continue balancing itself through gradual price adjustments and improved inventory levels. Highly desirable neighborhoods with strong job markets and quality schools often remain competitive, while areas with more available homes may offer buyers greater negotiating power.
Recent home value trends reported through the Zillow Home Value Index highlight how regional markets continue to perform differently, emphasizing the importance of analyzing local housing data before making a buying or selling decision.
For buyers, this means patience and preparation are more important than trying to perfectly time the market. For sellers, pricing a property realistically and presenting it in excellent condition remain key strategies for attracting qualified buyers.
Key Takeaways
- Mortgage rates remain one of the biggest drivers of housing affordability.
- Limited housing inventory continues to support home prices in many regions.
- Local real estate conditions matter more than national headlines.
- Buyers should focus on long-term affordability rather than short-term market fluctuations.
- Sellers who price homes competitively are more likely to attract serious offers.
Housing Inventory Explained
Housing inventory refers to the number of homes available for sale in a particular market. It is one of the strongest indicators of whether conditions favor buyers or sellers.
When inventory is low, buyers have fewer options, leading to increased competition and higher home prices. Conversely, when more homes are available, buyers gain greater negotiating power, and sellers may need to price their properties more competitively.
Several factors affect housing inventory, including new home construction, homeowner confidence, mortgage rates, and seasonal buying patterns. Understanding inventory levels can help buyers identify opportunities and sellers determine the right time to list their homes.
How Inventory Is Affecting Buyers Today
Housing inventory is one of the most important factors shaping the market. More homes for sale can give buyers greater choice and increase negotiating power, while limited inventory can keep prices firm even when buyer demand slows. The effect is especially important when mortgage rates are high because many existing homeowners are reluctant to give up older, lower-rate mortgages.
As a result, the housing market today can experience slower sales without a major drop in home prices. Buyers may see more price cuts, longer listing times, or greater opportunities to negotiate in some markets, while areas with tight inventory can remain competitive.
Should You Buy a Home Right Now?
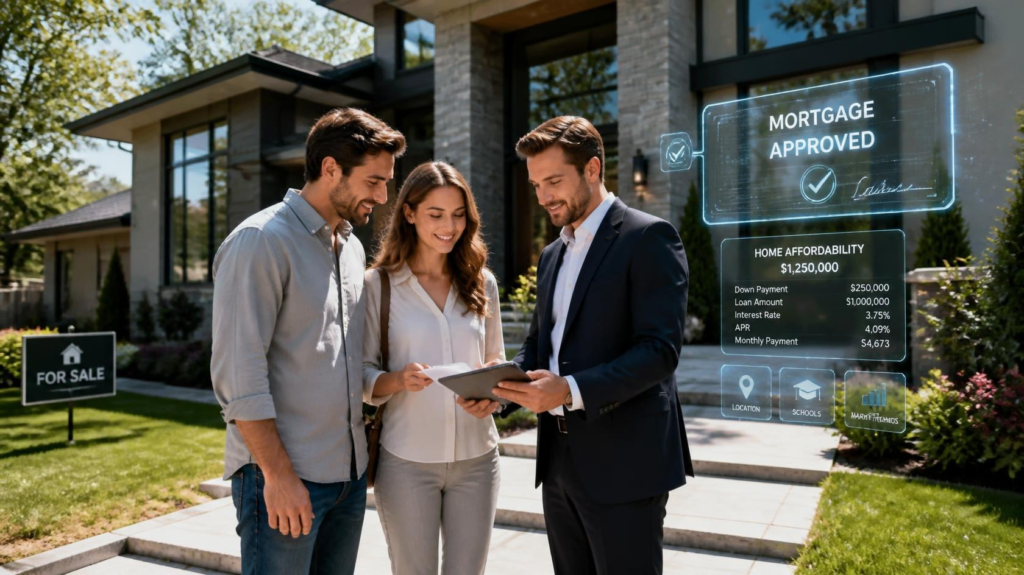
Buying a home is a significant financial decision that depends on your personal goals rather than market headlines alone.
You may be in a strong position to buy if you:
- Have a stable income and emergency savings.
- Can comfortably afford monthly mortgage payments.
- Plan to stay in the home for several years.
- Have a healthy credit score and manageable debt.
Instead of waiting for the “perfect” market, focus on purchasing a home that fits your long-term budget and lifestyle. Buyers who prepare financially and compare mortgage options are often better positioned than those trying to predict short-term market movements.
Is It a Good Time to Sell?
Many homeowners continue to benefit from strong property values, especially in neighborhoods where housing inventory remains limited.
Before listing your property, consider:
- Current home values in your area.
- Local buyer demand.
- Mortgage rates affecting potential buyers.
- The condition and presentation of your home.
Simple improvements such as fresh paint, landscaping, professional photography, and competitive pricing can make a property more attractive and help it sell faster.
Housing Market Forecast
While no forecast is guaranteed, many housing analysts expect the market to continue stabilizing as inventory gradually improves and buyers adapt to current mortgage rates. Future housing trends will also depend on inflation and interest rate decisions made by the Federal Reserve. , as these policies influence borrowing costs, consumer confidence, and overall housing demand.
Several factors will influence the housing market over the coming months:
- Mortgage rate movements
- Inflation trends
- Employment growth
- New home construction
- Consumer confidence
- Regional population growth
Instead of dramatic price swings, many experts anticipate moderate changes that vary by city and region. Buyers and sellers should monitor local market data rather than relying solely on national averages.
Modern real estate professionals are also using artificial intelligence to analyze housing trends, predict market movements, and improve property valuations. Learn more in our guide to What Is Artificial Intelligence? A Complete Beginner’s Guide.
Real Estate Investment Opportunities
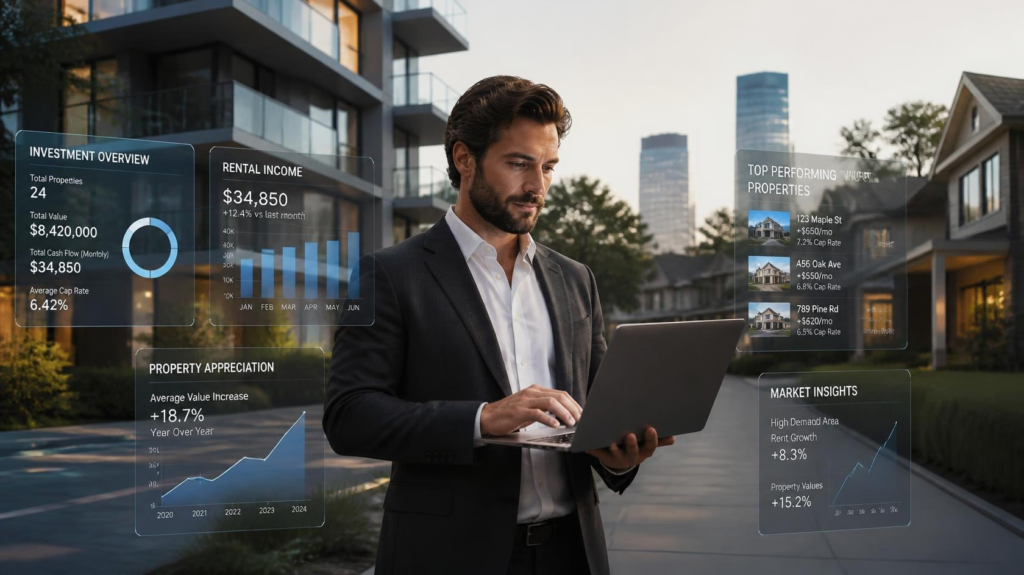
Real estate remains one of the most popular long-term investment options because it offers the potential for property appreciation, rental income, and portfolio diversification.
Popular investment opportunities include:
- Single-family rental homes.
- Multi-family residential properties.
- Vacation rentals.
- Real Estate Investment Trusts (REITs).
- Renovation and resale projects.
Before investing, evaluate market demand, financing costs, expected rental income, maintenance expenses, and long-term growth potential. Careful research and financial planning are essential for reducing risk and maximizing returns.
How Mortgage Rates Affect Housing Market Affordability
Mortgage rates have a direct effect on housing market affordability because they influence the monthly cost of borrowing. When mortgage rates rise, buyers generally qualify for smaller loan amounts or face higher monthly payments on the same home. When rates fall, purchasing power can improve even if home prices do not immediately decline.
For buyers evaluating the housing market today, the key is to consider the complete monthly cost rather than looking at the mortgage rate or home price alone. A realistic affordability calculation should include the mortgage payment, property taxes, homeowners insurance, maintenance costs, down payment, and other ownership expenses.
Rising housing costs can be especially challenging for retirees and people living on fixed incomes. If you’re wondering how future benefit increases could help offset higher living expenses, read our guide on the Social Security 2027 COLA Forecast: Latest Estimates, Payment Increase & What to Expect, which explains how projected Social Security adjustments may affect retirement budgeting and long-term financial planning.
What Buyers Should Watch in the Coming Months
Homebuyers should continue monitoring several important economic indicators that could influence mortgage rates and housing affordability.
These include:
- Federal Reserve policy decisions
- Inflation reports
- Employment data
- Mortgage rate trends
- Local housing inventory
- Home price changes
Because housing conditions can change quickly, staying informed can help buyers identify better opportunities and avoid unnecessary financial risks.
📌 What to Watch Next
✓ Weekly Mortgage Rate Trends
✓ Federal Reserve Meetings
✓ Inflation Reports
✓ Housing Inventory Updates
✓ Home Price Index Reports
EEZYPOST updates this guide whenever major mortgage rate changes or housing market developments occur.
Frequently Asked Questions
Is the housing market expected to crash?
Most analysts do not expect a nationwide housing market crash. Market conditions vary by location, and many areas continue to experience steady demand supported by limited housing inventory.
Will home prices fall?
Home prices may soften in some regions, but widespread declines are unlikely without significant economic changes. Local supply and demand remain the biggest drivers of property values.
Why are mortgage rates so important?
Mortgage rates directly affect monthly loan payments and overall affordability. Higher rates reduce purchasing power, while lower rates generally encourage more buyers to enter the market.
Is real estate still a good investment?
For many investors, real estate continues to provide long-term wealth-building opportunities through appreciation, rental income, and diversification. However, every investment should align with individual financial goals and risk tolerance.
Is now a good time to buy a home?
It depends on your financial situation, local market conditions, mortgage rates, and long-term plans. Buyers should compare financing options and calculate total monthly housing costs before purchasing.
Will mortgage rates go down?
Mortgage rates can rise or fall depending on inflation, Federal Reserve policy, and broader economic conditions. While experts publish forecasts, future rates cannot be guaranteed.
What affects housing market affordability the most?
Mortgage rates, home prices, household income, property taxes, homeowners insurance, and available housing inventory all influence housing affordability. Buyers should consider their total monthly housing costs instead of focusing only on the purchase price.
Why is housing affordability still a problem?
Housing affordability remains a challenge because home prices, mortgage rates, insurance costs, taxes, and limited housing supply continue to put pressure on household budgets in many markets.
Final Thoughts
The Housing Market Today continues to evolve as mortgage rates, home prices, and housing inventory respond to broader economic conditions. While market trends may shift from one region to another, informed buyers and sellers can make confident decisions by focusing on local data, financial readiness, and long-term objectives.
Whether you’re buying your first home, selling a property, or exploring real estate investment opportunities. EEZYPOST will continue updating this guide whenever mortgage rates, housing affordability, or major real estate trends change, ensuring readers always have access to the latest verified market insights.


John Walter
Very informative article. The explanation about mortgage rates and housing affordability was easy to understand. Looking forward to more housing market updates from EEZYPOST.