
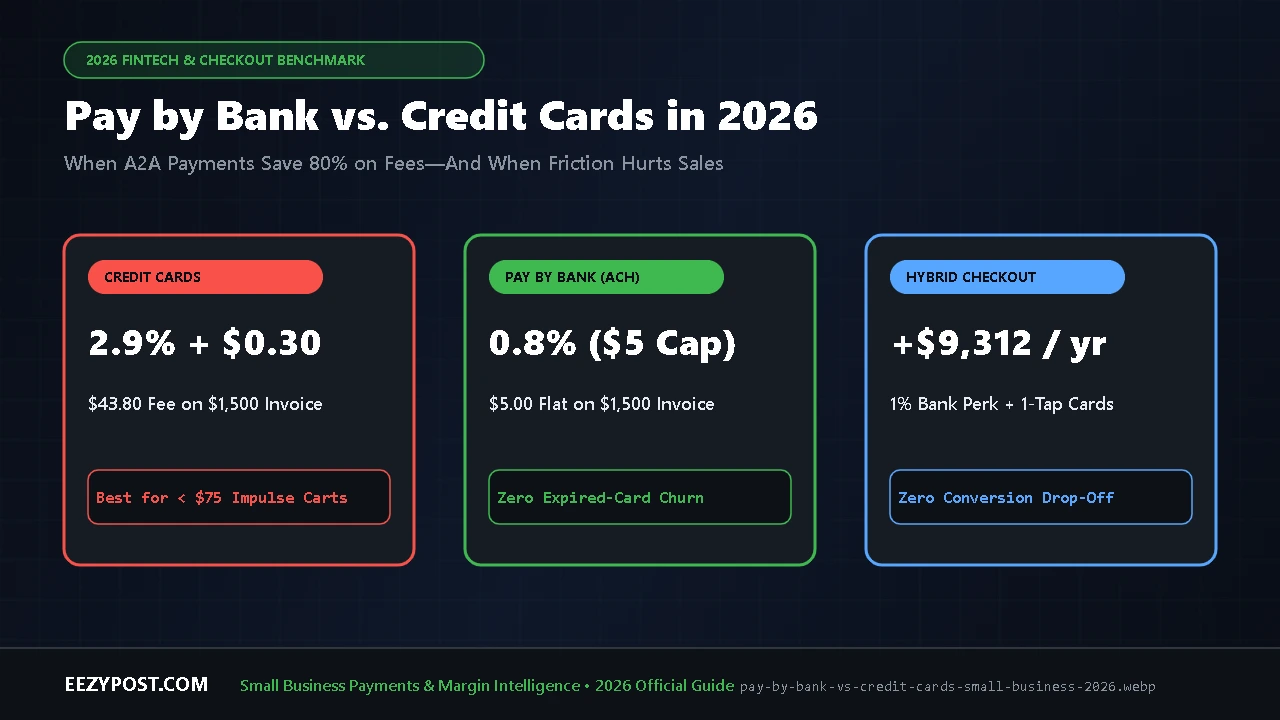
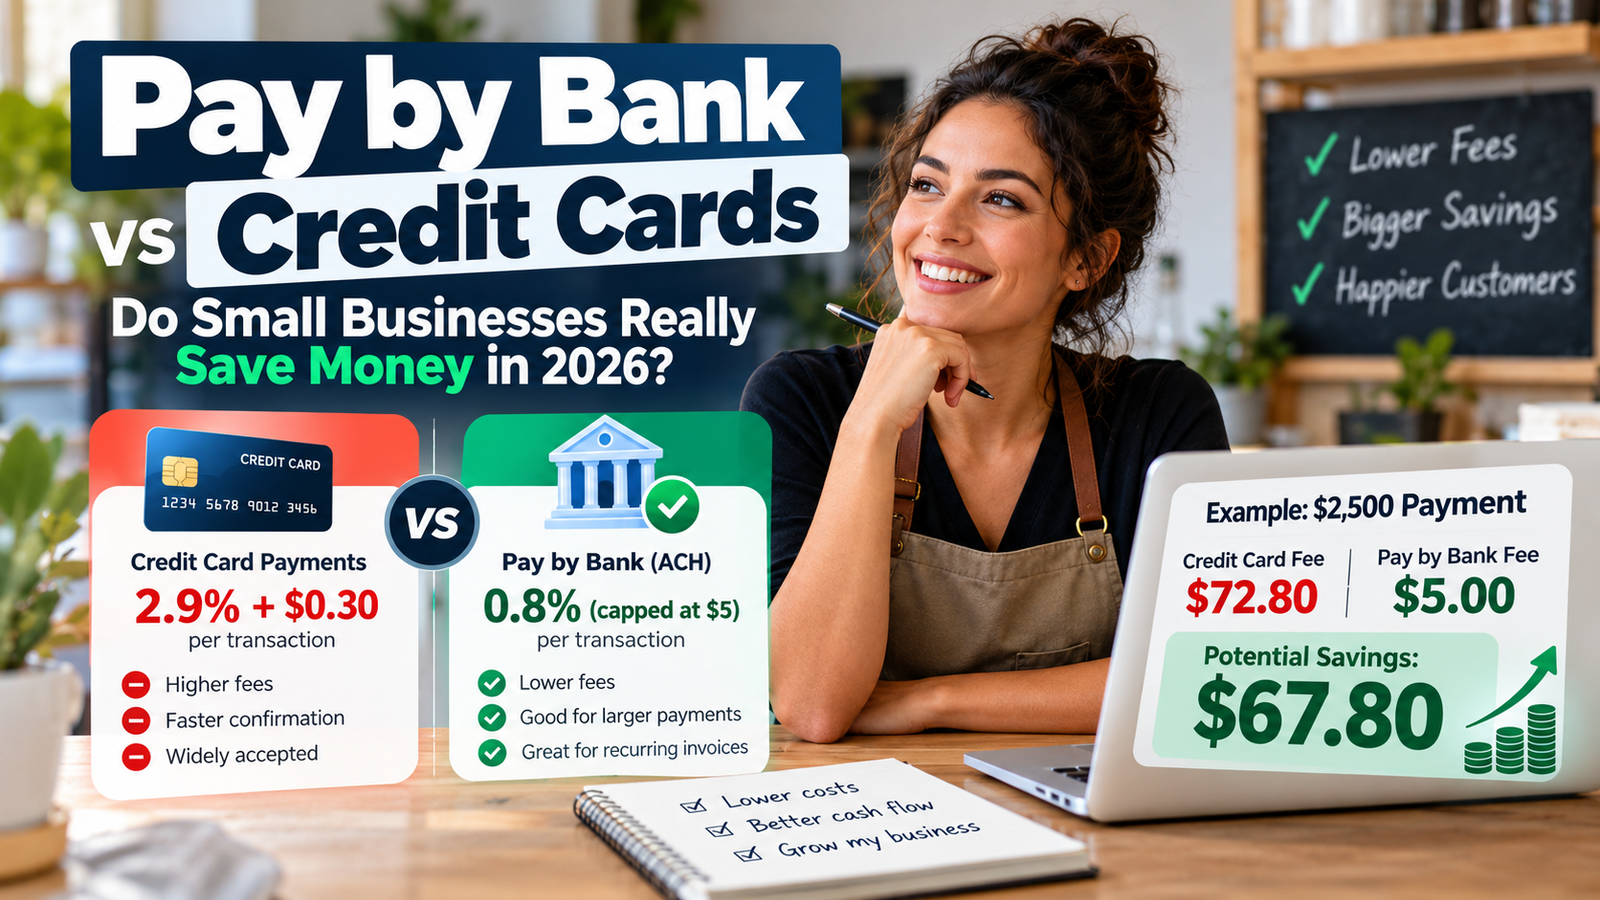
Evaluating pay by bank vs credit cards in 2026 comes down to a simple tug-of-war between processing fee recovery and checkout friction. On paper, routing customer payments directly from bank account to bank account (A2A) wipes out Visa and Mastercard interchange fees, slashing transaction costs by 50% to 85%. In reality, forcing the wrong customer segment to authenticate their bank app at checkout can trigger cart abandonment that wipes out every penny of your fee savings.
When I audited payment gateway statements across small service agencies and e-commerce stores this year, the pattern was unmistakable. On a $1,800 B2B wholesale or agency invoice, accepting a rewards credit card via Stripe burns $52.50 in pure processing fees—whereas a capped bank debit costs $5.00 flat. Yet on a $38 TikTok impulse purchase, pushing shoppers away from 1-tap Apple Pay toward a bank login flow tanked mobile checkout completion by 11%.
To win the pay by bank vs credit cards equation without hurting top-line sales, you have to match the payment rail to your Average Order Value (AOV) and buyer trust level. Here is the exact 2026 breakdown.
Pay by Bank vs Credit Cards: How A2A Rails Bypass Interchange in 2026
Every time a customer taps an Apple Pay wallet or types a 16-digit Visa number into your checkout, three separate middlemen take a cut before the cash hits your business checking account:
- The Card-Issuing Bank (Interchange Fee): Typically 1.80% to 2.50%+ (highest on premium travel rewards and corporate cards) to fund the buyer’s airline miles and fraud liability.
- The Card Network (Assessment Fee): Roughly 0.13% to 0.15% paid directly to Visa, Mastercard, or Amex simply for riding their rails.
- The Payment Processor Markup: The margin added by Stripe, Shopify Payments, or Square to bundle everything into a flat 2.9% + $0.30 online rate.
When you compare pay by bank vs credit cards, modern Account-to-Account (A2A) payments—powered by OAuth open-banking connections (like Stripe Financial Connections, Plaid, or Trustly) alongside Same Day ACH and instant RTP/FedNow settlement—cut out both the issuing bank’s rewards tax and the card network assessment.
Instead of typing routing and micro-deposit numbers like clunky 2019 bank transfers, 2026 Pay by Bank lets customers tap their bank logo, authenticate with FaceID inside their Chase, Bank of America, or Wells Fargo app, and authorize payment in under 10 seconds under modern Nacha Same Day ACH operating rules.
Pay by Bank Fees Small Business Owners Actually Pay vs Hidden Card Markups

Most fintech sales pages oversimplify pay by bank fees small business merchants pay by quoting a single domestic percentage while ignoring international card penalties, failed return fees, and chargebacks.
Here is the real side-by-side breakdown of pay by bank fees small business operators see on live 2026 merchant statements:
| Cost & Settlement Metric | Standard Online Credit Cards (Stripe / Shopify) | Pay by Bank (ACH Direct Debit + Open Banking) | Instant Real-Time Pay by Bank (FedNow / RTP Providers) |
| Standard Domestic Fee | 2.9% + $0.30 per charge | 0.8% (Capped at $5.00 max) | 1.0% to 1.5% (Often capped at $10) |
| International / Amex Surcharge | +1.5% intl (+1.0% FX = 5.4% + $0.30) | $0 (Domestic US bank rails only) | $0 (Domestic bank rails only) |
| Settlement Speed to Bank | 2 Business Days | 2 to 4 Business Days (Same-Day optional) | Instant (Seconds, 24/7/365) |
| Dispute / Failure Penalty | $15 to $29 Chargeback Fee + network monitoring | $4 to $15 NSF / ACH Return Fee (No card network strikes) | Irrevocable push or verified-balance pull |
| Recurring Subscription Churn | High (Cards expire or get reissued every 24–36 mos) | Near Zero (Bank accounts rarely close) | Near Zero |
Two hidden factors make pay by bank vs credit cards heavily favor bank rails for recurring and high-ticket businesses:
- Zero Expired-Card Churn: SaaS companies, retainer agencies, and membership boxes lose 5% to 9% of recurring revenue every year simply because stored credit cards expire or get replaced after unrelated fraud alerts. Linked bank accounts stay active for decades.
- Protection Against “Friendly Fraud”: With credit cards, a customer can consume a service or receive a shipment and click “Dispute Charge” inside their banking app 60 days later, hitting you with an automatic $15+ fee. Open-banking authenticated pulls verify live account ownership and available balance upfront, cutting fraudulent dispute rates dramatically.
ACH vs Stripe Card Fees: Real Dollar Math from $50 Carts to $2,500 Invoices
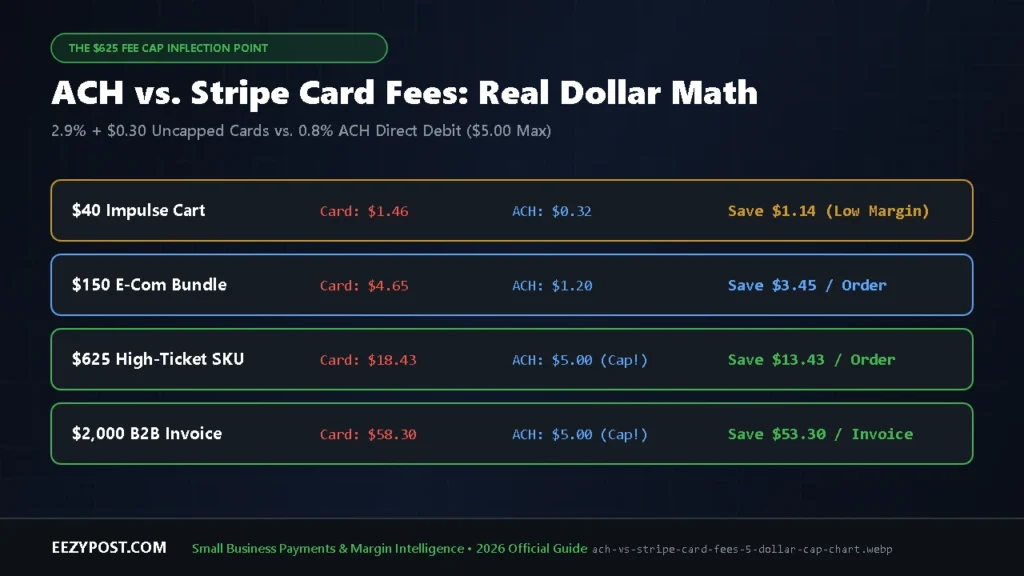
To see where ach vs stripe card fees diverge exponentially, look at Stripe’s $5.00 fee cap on ACH Direct Debit (0.8% up to $625; flat $5.00 above $625). Every dollar above $625 on a transaction is processed 100% free of percentage fees.
| Order / Invoice Size | Stripe Domestic Card Fee (2.9% + $0.30) | International Card Fee (4.4% + $0.30) | Pay by Bank / ACH Fee (0.8%, $5 Cap) | Net Cash Saved Per Transaction |
| $40 Impulse Order | $1.46 | $2.06 | $0.32 | +$1.14 (Warning: High friction risk) |
| $150 E-Com Bundle | $4.65 | $6.90 | $1.20 | +$3.45 |
| $625 High-Ticket SKU | $18.43 | $27.80 | $5.00 (Cap Hit) | +$13.43 to +$22.80 |
| $1,500 Agency Retainer | $43.80 | $66.30 | $5.00 | +$38.80 to +$61.30 |
| $5,000 Wholesale Order | $145.30 | $220.30 | $5.00 | +$140.30 to +$215.30 |
When comparing ach vs stripe card fees on 20 monthly client retainers of $1,500, switching clients from credit cards to Pay by Bank puts $776/month ($9,312/year) straight back into your operating account—with zero changes to your pricing or fulfillment.
Pay by Bank vs. Credit Cards Net Savings Calculator
Compare Stripe Card Fees (2.9% + $0.30) against Capped Pay by Bank / ACH (0.8%, $5 max)—including buyer adoption share and optional cashback incentives.
Recommended Setup: Display Pay by Bank alongside Apple Pay and cards at checkout. Even after giving customers a 1.0% instant bank bonus, you pocket +$3,486/year in pure fee savings with zero cart abandonment risk.
Open Banking Checkout Conversion Rate: Why Cheap Fees Can Hurt Low-AOV Stores
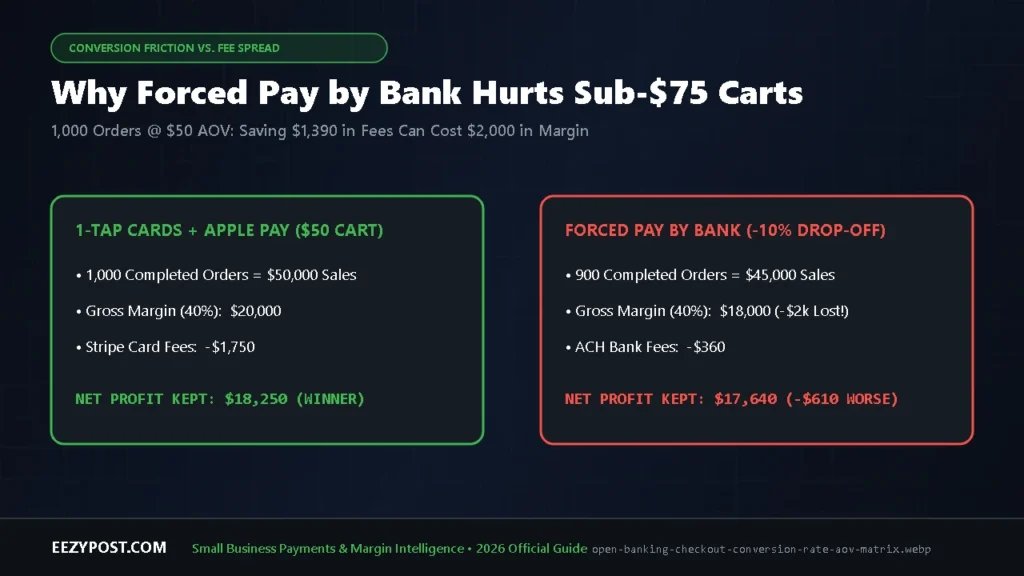
If Pay by Bank saves up to 80% on fees, why shouldn’t every Shopify store rip out credit cards tomorrow? Because open banking checkout conversion rate physics punish low-ticket impulse purchases.
When a shopper clicks one of your AI UGC ads vs human creators on TikTok at 11:30 PM for a $39 gadget, Apple Pay and Shop Pay require one thumbprint and 1.5 seconds. Selecting Pay by Bank for the very first time requires:
- Searching for their bank institution in a modal window.
- Authenticating via FaceID or typing banking credentials + a 2FA SMS code.
- Giving UP their 2% cash-back credit card rewards.
Across 2026 checkout benchmarks, forcing bank payments or hiding card options lowers open banking checkout conversion rate by 6% to 14% on cold first-time consumer traffic under $75.
Do the math on 1,000 checkouts for a $50 product with a 40% gross margin:
- 100% Cards: 1,000 orders = $50,000 revenue $\rightarrow$ $1,750 Stripe fees $\rightarrow$ $18,250 net contribution.
- Forced Pay by Bank (-10% Conversion Drop): 900 orders = $45,000 revenue $\rightarrow$ $360 bank fees $\rightarrow$ $17,640 net contribution (-$610 WORSE OFF).
Saving $1,390 in processing fees cost you $2,000 in lost gross margin! Never remove cards on sub-$100 consumer stores—always present Pay by Bank side-by-side with an instant cashback or discount incentive so card-loyal shoppers still convert.
How to Roll Out Instant Bank Payments for Ecommerce and B2B Without Losing Sales
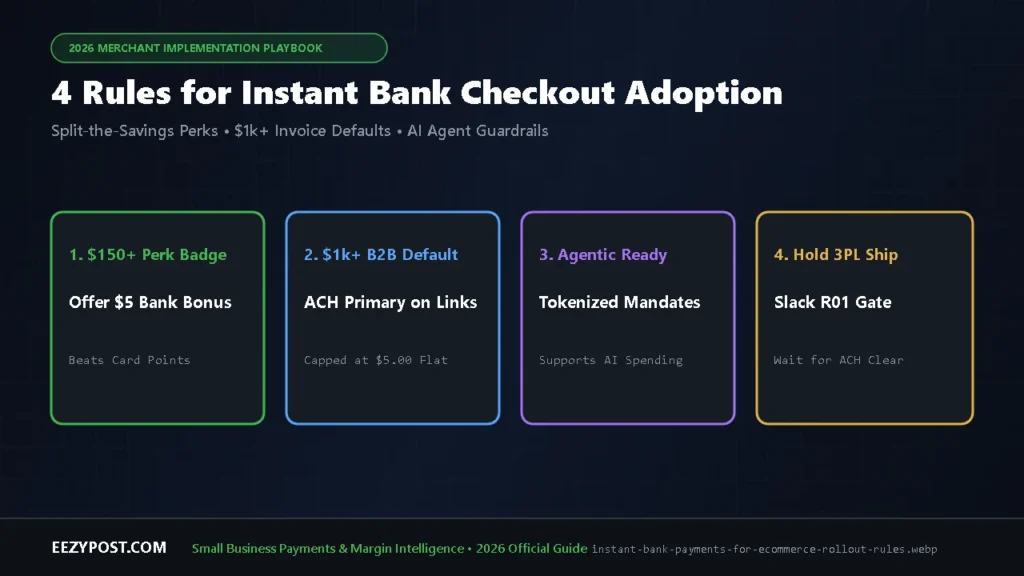
To capture the upside of instant bank payments for ecommerce and service invoicing without damaging checkout conversion, deploy these four practitioner rules:
1. Offer a “Split-the-Savings” Instant Incentive Above $150
On orders over $150—furniture, electronics, auto parts, wholesale bundles, or annual software plans—credit card fees exceed $4.65 to $30+. Add a native checkout badge next to Pay by Bank reading: “⚡ Instant $5 Off (or 1.5% Cash Bonus) When You Pay by Bank.” You share half of your interchange savings to neutralize the customer’s lost credit card points and still pocket pure margin. (Pair this checkout gain with our dimensional weight shipping ecommerce audit and you can often recover 4% to 8% of total store net profit in a single weekend).
2. Make Pay by Bank Mandatory (or Default) on Invoices Over $1,000
For agencies, contractors, and B2B wholesalers sending Stripe Payment Links or QuickBooks invoices over $1,000, toggle “Bank Transfer / ACH Only” as the default—or add a compliant convenience fee on credit cards where permitted by state rules. No small business should donate $87.30 to Visa on a $3,000 invoice.
3. Prepare Your Checkout for AI Shopping Agents
A massive 2026 shift in pay by bank vs credit cards involves autonomous purchasing. As we explored in our analysis of whether an AI shopping agent can buy something without your approval, programmable virtual cards and tokenized bank-rail mandates are becoming the primary guardrails consumers use to set hard dollar caps on AI-initiated orders. Keeping modern Stripe or Adyen unified checkouts enabled ensures your store supports both tokenized agentic cards and instant bank links automatically.
4. Wire Up Failed-Return Alerts via Human-in-the-Loop Automation
Unlike credit cards—which decline in 1 second if a card is maxed out—standard ACH bank debits can occasionally return R01 (Insufficient Funds) 48 hours after an order looks paid. Never auto-ship a $1,200 physical order paid via non-instant ACH until settlement clears, or connect your Stripe charge.dispute and payment_intent.payment_failed webhooks into one of our human in the loop AI workflows for small business to automatically pause 3PL fulfillment in Slack until funds settle.
Frequently Asked Questions (AEO Quick Answers)
How much do small businesses save with pay by bank vs credit cards in 2026?
When comparing pay by bank vs credit cards, small businesses typically save 50% to 85% on processing fees. While standard online credit cards cost 2.9% + $0.30 (with no maximum cap), Pay by Bank via ACH Direct Debit on platforms like Stripe costs 0.8% capped at $5.00, saving $13.43 on a $625 order and $53.30 on a $2,000 invoice.
Does Pay by Bank hurt ecommerce checkout conversion rates?
Removing credit cards hurt conversion, while offering instant bank payments for ecommerce alongside cards and digital wallets does not. On orders under $75, most shoppers prefer 1-tap Apple Pay or reward cards. On orders over $200, offering a 1% to 2% instant checkout discount for Pay by Bank shifts 18% to 30% of buyers onto low-cost bank rails with zero overall conversion loss.
Can customers file chargebacks on Pay by Bank transactions?
Pay by Bank transactions do not run on Visa or Mastercard rails, so they bypass card-network chargeback monitoring programs and $15–$29 card dispute fees. However, a customer can still dispute an unauthorized debit through their bank under Regulation E (resulting in an ACH return), which is why merchants should always use OAuth open-banking instant verification (like Plaid or Stripe Financial Connections) to verify live account ownership and balance before shipping high-ticket goods.
Leave a Reply